How to Save on Car Insurance in the U.S.: 8 Effective Strategies
Business & E-Commerce / Money Guide
The most effective savings usually come from comparing equivalent policies, correcting rating information and changing coverage deliberately—not from accepting the lowest number on a quote screen.
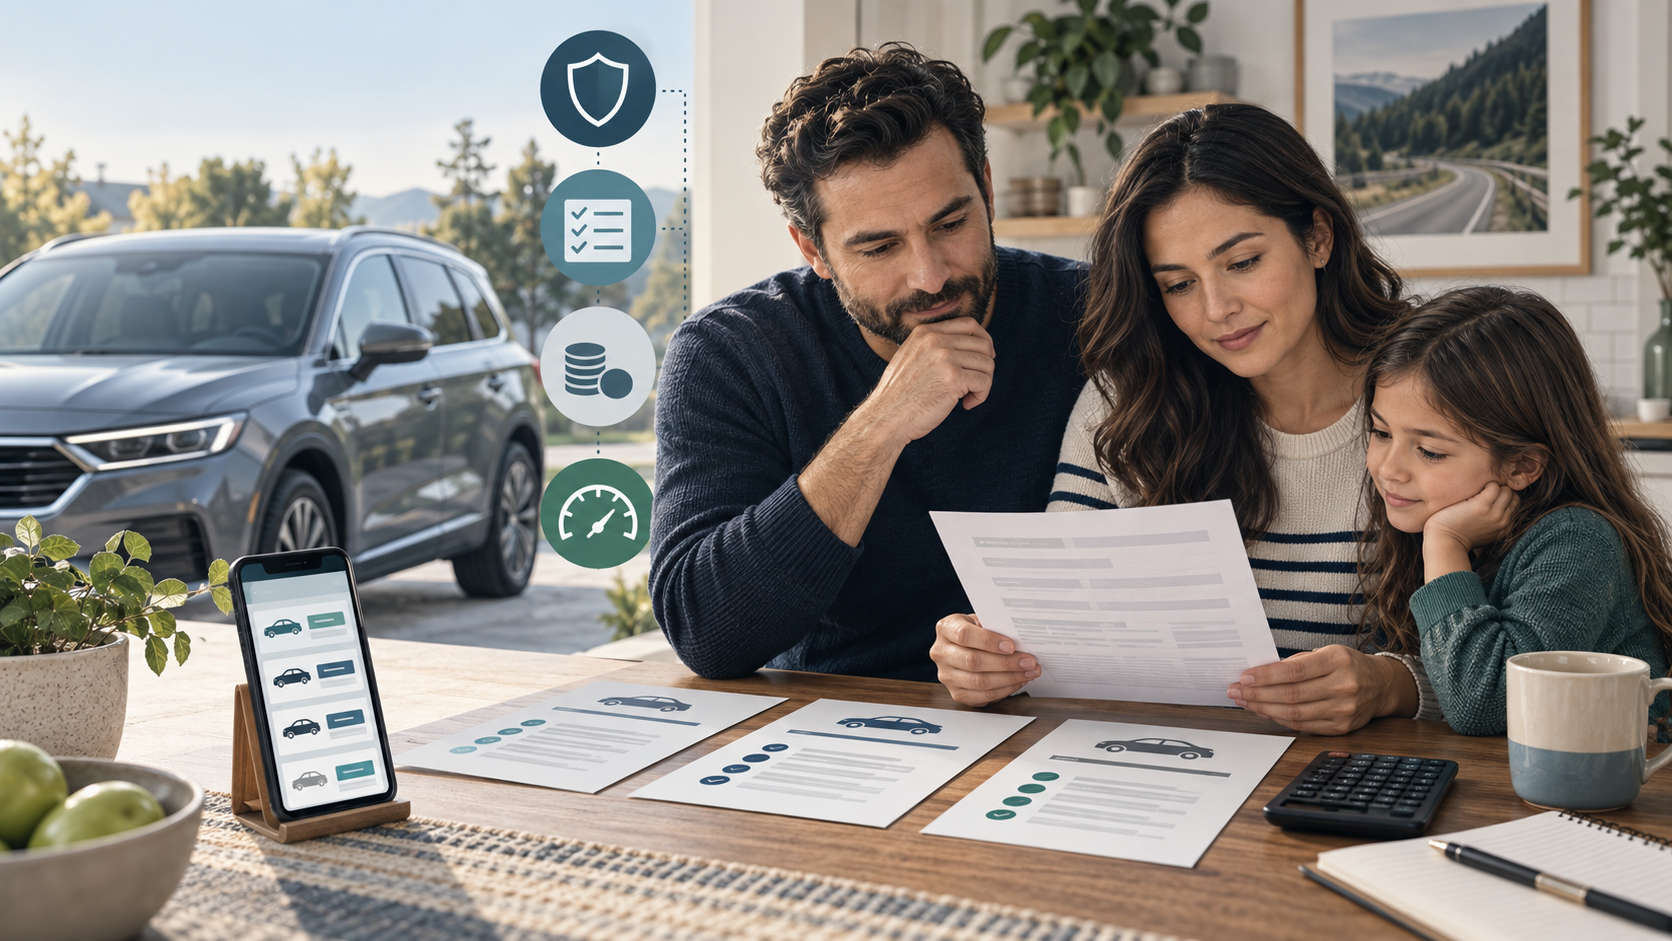
Editorial note: This guide provides general U.S. consumer information, not individualized insurance, legal or financial advice. Requirements and rating rules vary by state. The featured image is an original editorial illustration.
Auto insurance is expensive enough that almost any advertised discount can sound attractive. The problem is that two prices may represent very different protection. A policy can look cheaper because it carries lower liability limits, a larger deductible, fewer optional coverages or exclusions that only become obvious after a crash.
A better savings plan starts with a complete copy of the current declarations page. That document lists the insured vehicles and drivers, coverage limits, deductibles, discounts and premium. It gives you a common specification to use when requesting competing quotes.
Ask each insurer to quote the same drivers, vehicles, liability limits, deductibles and optional coverages. A lower premium is meaningful only when the protection is genuinely comparable.
1. Compare several insurers using the same coverage
The Consumer Financial Protection Bureau recommends shopping among multiple providers and comparing coverage as well as cost. Prices can differ because insurers weigh risk factors differently, even when the household and vehicle are unchanged.
Request quotes before the existing policy renews, leaving time to resolve questions. Include at least one direct insurer and, where available, an independent agent who can quote several companies. Record the full-term premium, payment fees, liability limits, deductibles and included services. Do not compare one six-month figure with another company’s annual figure.
2. Audit the information used to price the policy
The National Association of Insurance Commissioners advises consumers to verify addresses, vehicle classifications, makes and models, driver ages and every applied discount. Also review which household member is listed as the principal driver of each car and whether the annual mileage remains accurate.
A job change, retirement, remote-work schedule or shorter commute can reduce annual driving. Tell the insurer when a car is driven materially less, but report mileage honestly. Incorrect garaging, driver or usage information can create problems when a claim is reviewed.
3. Raise the deductible only when the cash is available
A higher collision or comprehensive deductible can lower the premium because the policyholder accepts more of the initial loss. The savings is useful only if the household can pay that deductible after an unexpected accident, theft or storm.
Ask for prices at several deductible levels. Then divide the additional deductible by the annual premium savings. If moving from $500 to $1,000 saves $100 a year, the household accepts $500 more risk to save $100 annually. Keep the chosen deductible in an accessible emergency fund.
4. Review collision and comprehensive on an older vehicle
NAIC guidance says owners of older vehicles may consider reducing or eliminating physical-damage coverage after weighing the car’s value, repair or replacement cost and premium savings. This decision concerns damage to your own vehicle; it is separate from liability protection for injuries or property damage caused to others.
A lender or leasing company may require collision and comprehensive. Even without a loan, removing them can be a poor trade if losing the vehicle would prevent the owner from working or if replacing it would be financially difficult. Ask what the insurer would likely pay after depreciation and the deductible, then compare that potential benefit with the yearly cost.
5. Ask for every available discount—and verify it appears
Discounts differ by company and state. Common examples identified by the NAIC include insuring multiple vehicles, combining auto with homeowners or renters insurance, approved driver-education courses, good-student qualifications, safety equipment, anti-theft devices, claim-free history and certain payment arrangements.
Bundling is not automatically the cheapest choice. Compare the combined price with the cost of buying each policy separately, and compare the actual coverage. Convenience can be valuable, but it should not hide a weak homeowners or auto policy.
6. Evaluate telematics and usage-based insurance carefully
Usage-based programs can use a phone app or vehicle device to evaluate mileage and driving behavior. They may benefit a low-mileage driver with steady habits, but program rules differ. Before enrolling, ask which behaviors are measured, how long data is retained, whether the program can increase as well as decrease the premium, and what happens when another family member drives.
Read the privacy notice and estimate the likely benefit before exchanging driving data for a possible discount. A traditional low-mileage discount may be available without continuous behavior monitoring.
7. Price insurance before choosing the next car
Repair cost, theft experience, safety performance and claim severity can affect the price of insuring a model. Obtain insurance estimates for each vehicle on the shopping list before signing a purchase or lease agreement. A similar car with a lower purchase price can still cost more to insure.
When financing, distinguish ordinary auto insurance from optional credit products sold at the dealership. The CFPB advises consumers to compare insurance before buying the vehicle and to understand each additional product rather than treating it as a required part of the loan.
8. Protect the factors that improve future pricing
A clean driving record remains one of the strongest long-term tools. Avoiding tickets and preventable crashes can matter more than a small promotional discount. Where state law permits credit-based insurance scoring, credit information may also affect premiums. Check credit reports for errors and pay obligations on time rather than carrying debt merely to influence a score.
What should not be cut casually
State minimum liability limits can be far below the cost of a serious collision. Reducing liability coverage to the legal minimum may save money now while exposing wages, savings and property later. Uninsured or underinsured motorist protection, medical payments and personal injury protection also serve different purposes depending on state law and household health coverage.
Ask a licensed agent or the state insurance department to explain unfamiliar coverage. If a quote is dramatically lower, identify exactly what disappeared. The safest target is a lower price for protection that still fits the household’s realistic worst-case loss.
A renewal checklist that takes less than an hour
- Collect the declarations page and confirm every driver, vehicle, address and mileage figure.
- Choose the liability limits and deductibles that each quote must match.
- Request several quotes for the same coverage and policy term.
- List discounts separately and confirm they appear in the final documents.
- Check the insurer and complaint resources through the state insurance department.
- Cancel an old policy only after the replacement coverage is active, avoiding a lapse.
Effective savings come from repeating this review periodically, especially after a move, job change, marriage, teen driver, vehicle payoff or major change in mileage. The goal is not simply the smallest premium. It is the lowest sustainable cost for coverage the household can depend on.